Standard Asset Types

Apartment Complex Valuation (Multifamily)

Overview

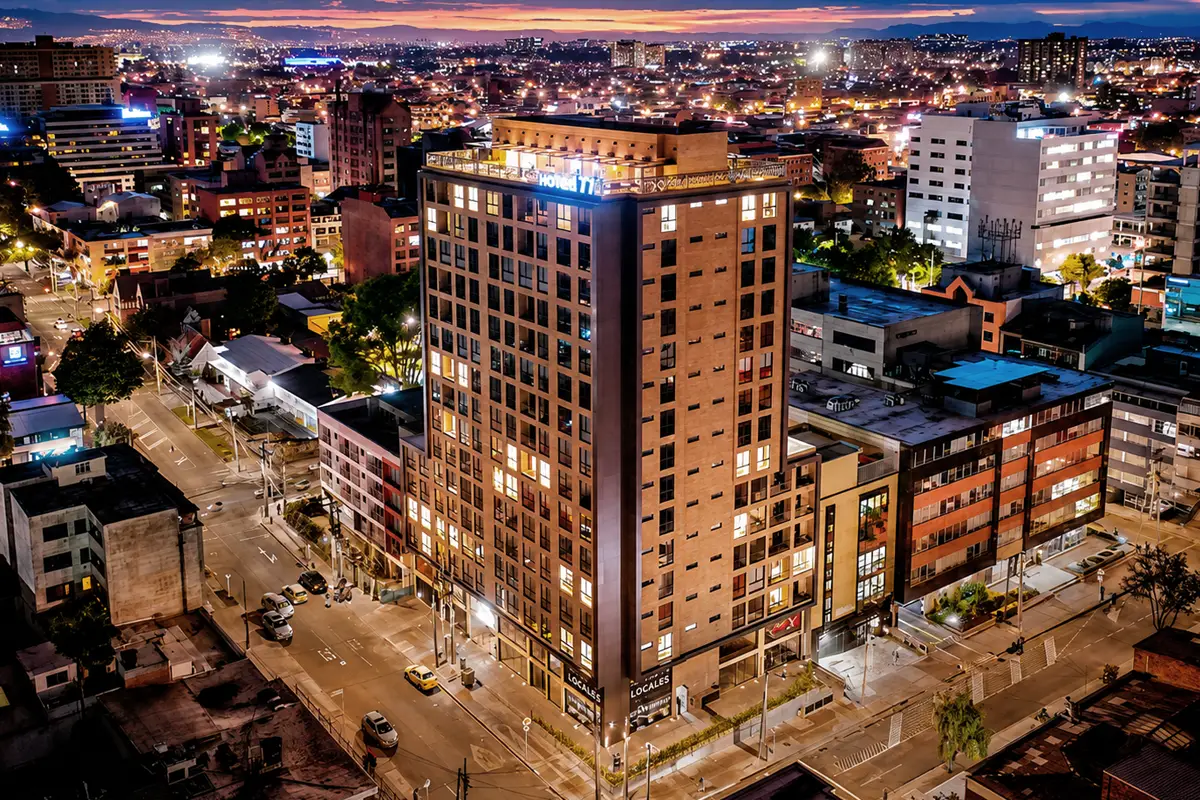
Apartment Complex, Multifamily Appraisal – Multifamily is a relatively new product type in Latin America and is considered to be growing in importance. Multifamily is defined as apartment projects that is rented rather than sold. This allows for complete management of the property by one ownership entity. Some of the benefits of multifamily properties include the ability to lease – show apartments continuously, plan out lease maturities, and remodel common areas continuously.

LOGAN offers and has completed multifamily or apartment appraisals of projects in Mexico, Colombia, Peru, and other countries in Latin America. As the asset class grows, LOGAN is prepared to grow its multifamily appraisal practice.

Types

High-rise – so far, most multifamily projects in Latin America have been high rise projects located in higher demographic areas. This is likely due to the expensive land located in infill locations and the higher quality (lower delinquency) tenants who locate in such areas.

Mid-rise – mid-rise projects have not been commonly developed in Latin America. This product type is one that can be built cheaply in the US by means of wood frame construction. This construction style is not commonly employed in Latin America.

Garden style – this multifamily type has not been built in Latin America, but could be someday in future master planned communities.


Approaches, Relevance

Cost – this approach is relevant, if the property is recently constructed.

Sales comp or market approach – there are so few multifamily comparable sales in Latin America, this approach has little relevance.

Income capitalization – A good approach as it considers the income of the property.

DCF – Most often the strongest valuation method, as the DCF allows for the modeling of future cash flows and costs.


Value Impacting Factors

Location – infill locations often have stronger demand, longer average lease terms, less turnover, and less delinquencies.

Amenities – amenities of a property often differentiate it from the ‘shadow market’ – the apartments that are bought by individual owners than rented. Often in Latin America, the shadow market has apartment properties with little or no amenities and is a differentiator for multifamily projects that typically do.


Important Inputs

Delinquencies – non-payment. This varies by market, but is an important factor closely related to renter protection laws. These laws are common in Latin America and have been one of the factors that has impeded significant investment of the asset class.

Rental growth rate – often at inflation or slightly above.

Other income – this includes extra charges such as laundry, pet fees, etc.

Average lease length – frictional vacancy.
Recent Trends

  • Regional platforms of multifamily in Latin America that integrate investment, construction and operation.
  • New projects being undertaken as the uncertainty of the asset class is diminishing.

Deliverable

Narrative Appraisal Report

A. Value impacting considerations – summary.
B. Purpose, scope, limitations of the report.
C. Land description.
D. Improvement description.
E. Scope of work.
F. Highest and best use.
G. Approaches to value.
H. Reconciliation.
I. Certification statement

Notable Markets


Colombia México Perú CR-CA
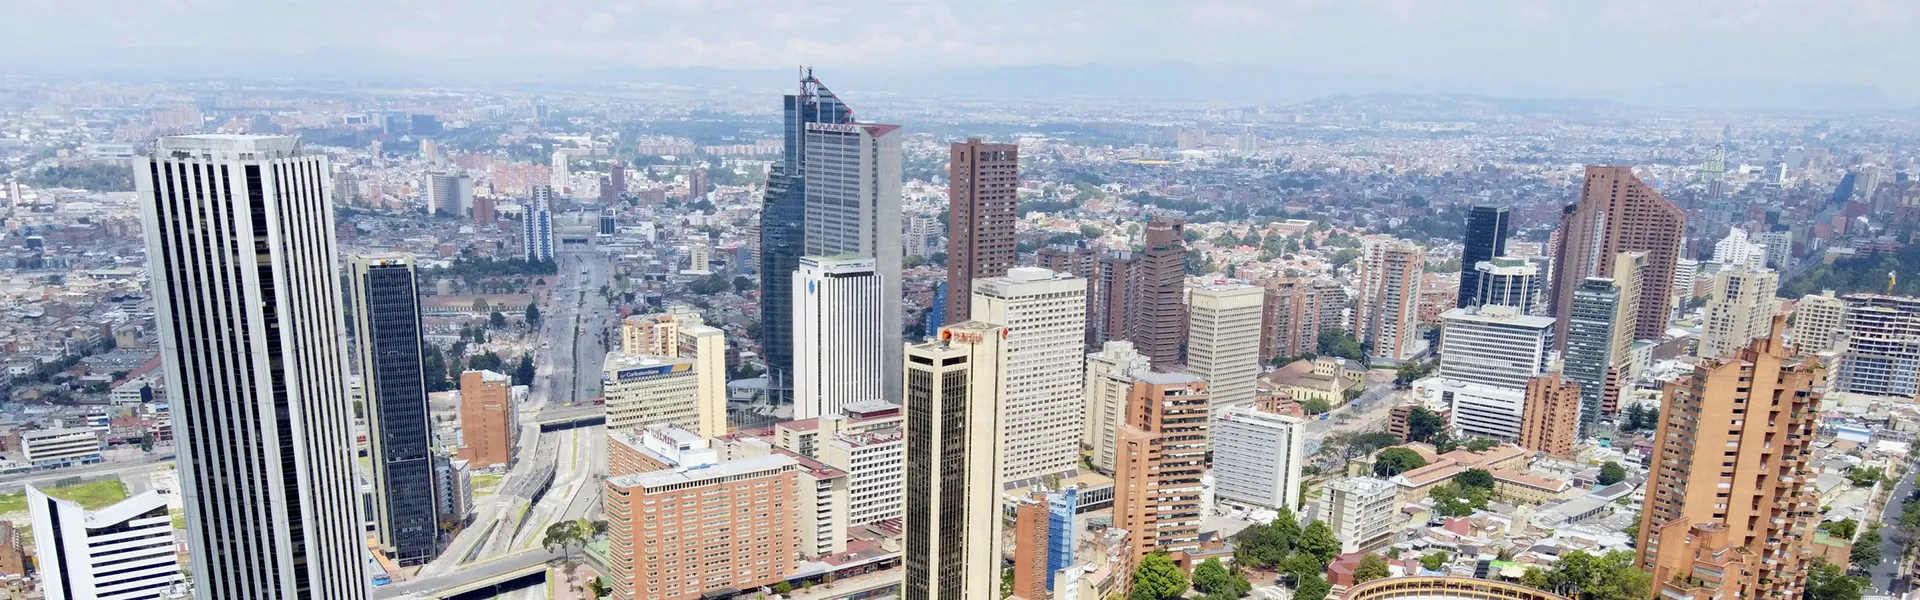
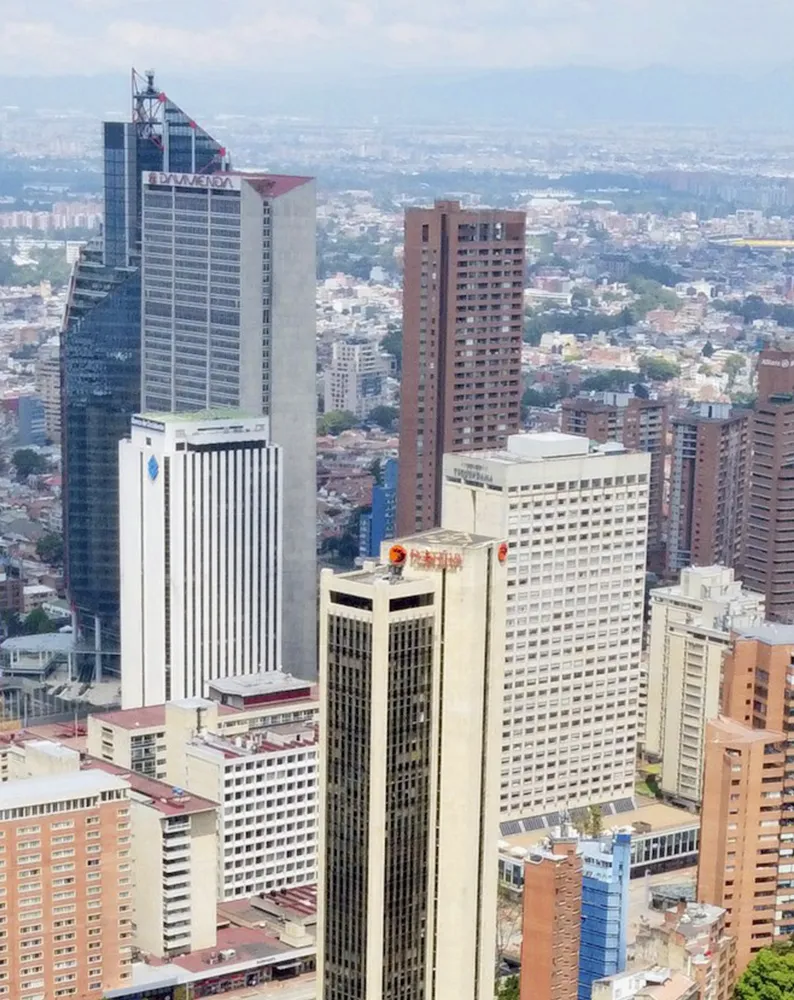
1 Bogota, 26 Ave DF, Polanco Lima, Miraflores San Jose, Escazu
2 Bogota, Chico DF, Santa Fe Lima, San Isidro Panama City
3 Medellin, Ave. Poblado Nuevo Leon, Monterrey Lima, Santa Cruz Guatemala

Leadership Team

Leadership Across Latin America's
Principal Markets.

Other case studies

CCLA – Multifamily Market Study Colombia

Project Leaders: Diego Rodriguez Rueda, MRICS; Paola Raba. Market analysis for the first institutional Multifamily project in Colombia, Nomad 77 (127 Units).

BASE PG – Office Market Study Colombia

Project Leaders: Diego Rodriguez Rueda, MRICS; Jessica Suarez Needs Market information for use with investors, banks, and for management.

Local teams. Regional standards.
One point of contact.

81st Street # 11-55, Ochenta 81 Building, North Tower, 6th Floor, Office 601, Bogotá, Colombia

Email: adminCO@loganvaluation.com
Phone: +57 (601) 467-4717
Hours: M - F 8.00 am - 5.30 pm

217 Mayor Armando Blondet Street, Office 901, San Isidro, Lima, Peru

Email: adminPE@loganvaluation.com
Phone: +51 (1) 702-7126
Hours: M - F 8.00 am - 5.30 pm

San Rafael de Escazu, District 4 North Coast – Amara CC, Office 408, 10203, Costa Rica

Email: AdminCA@loganvaluation.com
Phone: +506 4010-0565
Hours: M - F 8.00 am - 5.30 pm

Plaza Villa de Madrid No. 1, 10th Floor – Office “C,” Roma Norte, Cuauhtémoc, ZIP Code 06700, Mexico City, Mexico

Email: adminMX@loganvaluation.com
Phone: +52 (55) 9303-5017
Hours: M - F 8.00 am - 5.30 pm

86 Rafael Augusto Sánchez Street, Roble Corporate Center, 7th Floor, Office 10148, Santo Domingo, Dominican Republic

Email: adminCB@loganvaluation.com
Phone: +1 (849) 936-3683
Hours: M - F 9:00 am - 6:30 pm

Av. El Golf 40, 12th Floor, Las Condes, Santiago, 7550107

Email: AdminCH@loganvaluation.com
Phone: +56 (2) 2485-1345
Hours: M - F 8.00 am - 5.30 pm

Calle A-1, Urb. El Parque. Delta Tower, 6th Floor, Office No. 6-E, Barquisimeto, Lara State, Venezuela

Email: AdminVE@loganvaluation.com
Phone: +58 0424-5344823
Hours: M - F 8.00 am - 5.30 pm

Diagonal 6, 10-50, Zone 10, Interamericas Building, North Tower, Office 1601, Guatemala City, Guatemala

Email: adminCA@loganvaluation.com
Phone: +502 2294 4393
Hours: M - F 8.00 am - 5.30 pm
This site is registered on wpml.org as a development site. Switch to a production site key to remove this banner.